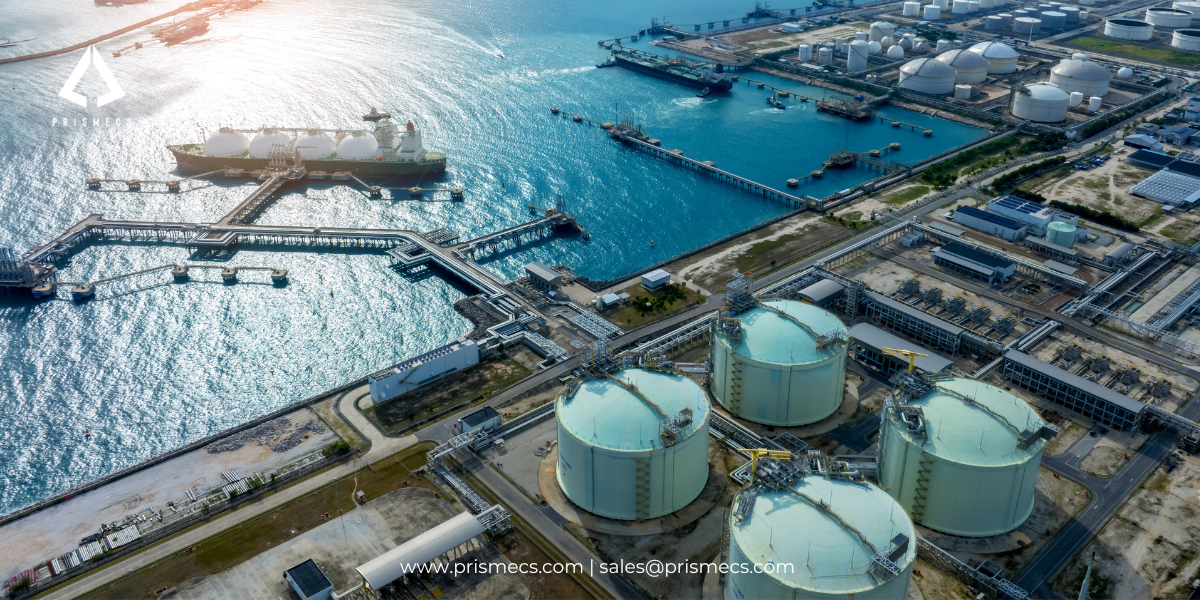
For an operator, the energy transition does not arrive as a portfolio decision. It arrives as a power problem on a site that was never designed to have power.
Replacing gas-driven pneumatic controllers with zero-emission equivalents needs electricity at wellpads that have none. Electrifying compression turns a fuel-gas consumer into a load. Electric fracturing needs tens of megawatts delivered to a location for a few weeks. And the grid you would normally ask is now queuing behind data centres for the same interconnections and the same transformers.
This guide covers the four forces creating that demand, the regulation driving the first one, where the power realistically comes from, and how to decide between grid, self-generation and hybrid on a specific site.
Scope note: this addresses power infrastructure decisions at operating oil and gas facilities. Corporate portfolio strategy and long-range demand scenarios are covered better by McKinsey, the IEA and the EIA, and are referenced here only where they change an operational decision.
What the Transition Looks Like at Site Level
At an operating facility, the transition presents as four concrete requirements: reduce methane emissions, reduce fuel consumption, reduce emissions intensity per barrel, and do all three without losing production.
Three of the four are achieved by replacing something that burns gas with something that uses electricity. That is what makes this a power infrastructure problem rather than an environmental one.
An operator who electrifies compression, converts pneumatics, adds e-frac capability or builds an LNG train is making the same decisions a utility makes: load profile, generation technology, interconnection, redundancy, and who operates it. Oil and gas organisations are generally not structured to make those decisions, because historically they did not have to.
The commercial framing
Emissions performance has moved from a reporting obligation to a condition of operation and, in some markets, of sale. That changes it from a cost to a constraint, and constraints get capital.
The Four Forces Making You a Power Buyer
Four separate drivers converge on the same outcome, and most operators are exposed to at least two of them.
Regulation. The US methane rules push operators toward zero-emission pneumatic systems, which require electrical power or instrument air at locations that have neither.
Operating cost and fuel. Electric drives are more efficient than gas drives at most duties, and fuel gas consumed on site is gas not sold.
Emissions intensity as market access. Methane intensity is increasingly a condition of LNG offtake and of access to some markets, which converts an environmental metric into a commercial one.
Production growth against grid constraint. Where load grows faster than the local network can serve it, the operator becomes a generator by necessity.
Where CCS fits, honestly
Carbon capture and storage is a real technology for large point sources, and it is capital-intensive, parasitic on plant efficiency, and dependent on transport and storage infrastructure that does not exist at scale in most basins. It is not an alternative to the four forces above and it does not solve a power problem. Treat it as a separate decision for a separate asset class.
For the hydrogen pathway, which is adjacent and frequently conflated with this, see our analysis of hydrogen in gas turbines and our guide to green hydrogen and net zero.
Zero-Emission Pneumatics and Where the Power Comes From
Pneumatic controllers that vent natural gas are being replaced under US methane rules, and the replacement needs a power source that most wellpads do not have.
A pneumatic controller is a device that uses pressurised gas to actuate valves and regulate process variables such as level, pressure and temperature. On a conventional wellpad the motive gas is the produced natural gas itself, and the controller vents that gas to atmosphere as part of normal operation. A pneumatic pump works the same way and vents for the same reason.
40 CFR Part 60 Subpart OOOOb emphasises the adoption of advanced technologies for pneumatic controllers and pumps, with operators moving to zero-emission pneumatic systems.
What replaces them
Electric actuation, which requires site electrical power.
Instrument air systems, in which an air compressor supplies clean dry air instead of natural gas, and the compressor requires electrical power.
Nitrogen supply, used where power is genuinely unavailable, supplied from bottles or a cryogenic vessel and requiring logistics rather than power.
The first two need electricity. The third needs a delivery schedule to a remote location indefinitely.
The problem this creates
A wellpad running gas-driven pneumatics needs no electrical supply beyond small solar panels for telemetry. Converting to electric actuation or instrument air creates a continuous load at a site with no service, and multiplying that across a pad count turns a compliance project into a power infrastructure programme.
That is the single most common route by which an upstream operator discovers they now have a power problem.
Electrifying Compression and Pumping
Replacing gas-driven compressor and pump drivers with electric motors removes an on-site combustion source, converts fuel gas into saleable gas, and creates a large continuous electrical load.
Gas-driven reciprocating and centrifugal compressors are the largest combustion sources on most gathering and processing systems. Replacing the driver with an electric motor eliminates the associated emissions at source, removes the driver's maintenance burden, and typically improves availability because electric motors have fewer wear components than gas engines.
Three things determine whether it is worth doing.
The delivered power price against the fuel gas value. Fuel gas consumed on site has an opportunity cost equal to what it would have sold for, less gathering and processing. Where gas prices are high, electrification looks better. Where power prices are high, it looks worse. Both move.
Whether the power can be delivered at all. This is usually the binding constraint, not the economics.
The emissions consequence. Electrification moves emissions from Scope 1, direct on-site combustion, to Scope 2, purchased electricity, and the net climate benefit depends on the carbon intensity of the supplying grid. Be explicit about which you are reducing, because a reduction in Scope 1 achieved by increasing Scope 2 is a reporting change rather than an emissions change.
Electric fracturing
Electric fracturing, or e-frac, replaces diesel-engine-driven pressure pumping with electric motors, typically drawing tens of megawatts for the duration of a completion.
The load is large, short-duration and mobile, which makes it a poor fit for a permanent grid connection and a good fit for temporary or relocatable generation. It is also the clearest case in the sector where the power solution moves with the operation rather than the operation moving to the power.
For deployment timelines, rating classes and contract structures on mobile and temporary capacity, see our guide to temporary and mobile power.
Where the Power Comes From
Three options exist for any oil and gas site load: take it from the grid, generate it on site, or combine both. The choice is usually decided by schedule rather than by cost.
Hosting capacity is the additional load or generation a distribution feeder can accommodate without violating voltage, thermal or protection limits. Utilities increasingly publish hosting capacity maps, and checking yours before selecting a site is cheaper than discovering the limit during the study.
Why the grid answer has got harder
US electricity demand is at record levels. EIA forecasts electricity sales reaching 4,135 billion kilowatt-hours in 2026, almost 2 percent above 2025, with a further 2 percent growth in 2027, driven by data centre development and increased manufacturing activity.
Oil and gas operators are now competing for the same interconnection capacity, the same transformers and the same switchgear as data centre developers who move faster and pay more. That competition, more than any technical factor, is why self-generation has become the default answer on schedule-driven projects.
For equipment lead times and how they set the procurement critical path, see our guide to the industrial procurement process.
Technology selection
Where self-generation is the answer, the technology choice turns on capacity factor, fuel availability and footprint. Reciprocating gas engines suit cycling duty and modular expansion. Gas turbines suit larger continuous blocks and constrained footprints. For heat rate, capacity factor and configuration selection, see our guide to power generation systems compared.
Where storage is part of the configuration, see our guide to battery energy storage systems. Where the generation will export or run in parallel with the utility, interconnection is governed by IEEE Std 1547-2018 and covered in our guide to distributed energy resources.
Ownership
Generation on an oil and gas site can be owned by the operator, leased, or supplied under a power purchase arrangement by a third party who owns and operates the asset. Ownership determines capital treatment, who carries the O&M obligation and who holds the emissions on their books. Decide it at feasibility, not after the equipment arrives.
If the schedule cannot wait
Temporary or relocatable generation bridges the gap between a required in-service date and a permanent solution, and on e-frac and drilling campaigns it is the permanent solution. Establish the bridge before the schedule is committed, not after it slips.
Associated Gas to Power
Associated gas produced with oil is frequently flared for lack of an outlet, and using it to generate the site's own power converts a disposal problem into a fuel supply.
Associated gas is natural gas produced in association with crude oil. Where gathering infrastructure is absent, undersized or offline, the gas is flared, vented or reinjected. Routine flaring, meaning flaring during normal production rather than for safety or maintenance, is under regulatory and commercial pressure in most producing jurisdictions.
Generating power from that gas addresses three things at once: it reduces flaring volume, it supplies the load created by electrification, and it avoids importing power.
What makes it difficult
Composition variability. Associated gas is wet, variable and often contains heavier hydrocarbons, H2S or CO2. Generation equipment has a fuel specification, and the gas must be conditioned to meet it. Budget the conditioning skid, not just the generator.
Volume decline. Associated gas volume falls with the well's production curve, so a generator sized for initial volume is oversized within a few years. Modular capacity that can be relocated is usually better than a single large unit.
Intermittency. Production upsets interrupt fuel supply. Dual fuel capability or a grid connection as backup protects against an outage caused by the process the power is serving.
Waste heat. Where a thermal load exists, recovering exhaust heat improves total fuel utilisation materially. Most upstream sites do not have a coincident thermal load, so check before assuming it.
Methane and Emissions Compliance
The US methane framework for oil and gas sits in two subparts of 40 CFR Part 60, and parts of it have been deferred, so the current position must be confirmed rather than assumed.
Subpart OOOOb regulates methane as a greenhouse gas, and also VOC and SO2, from affected facilities in the crude oil and natural gas source category. Subpart OOOOc functions as a model rule that states implement through their own plans.
The current position is in flux, and this matters
Several provisions have moved since the rules were finalised. The Waste Emissions Charge established under the Inflation Reduction Act was repealed by Congressional Review Act action, and Congress prohibited EPA from collecting it until 2034. EPA proposed delaying the Greenhouse Gas Reporting Program Subpart W programme until 2034, and in November 2025 finalised deadline exemptions for certain provisions of the OOOOb and OOOOc rules.
Confirm your current obligations with your air permitting adviser rather than relying on any article, including this one. An operator planning capital against a requirement that has been deferred, or ignoring one that has not, is exposed either way.
Super-emitter provisions
A super-emitter event is defined in the rule as any emissions event at or near an oil and natural gas facility, detected using remote detection methods, with a quantified emission rate of 100 kilograms per hour of methane or greater. On receiving EPA notification of such an event, the owner or operator must act within five calendar days.
The super-emitter provisions do not apply between 31 July 2025 and 22 January 2027, and apply after 22 January 2027. That is a dated compliance cliff worth putting in a calendar now, because the detection and response capability it requires takes longer than five days to build.
Market access
Methane intensity is increasingly a condition of sale rather than only a reporting metric, particularly for gas entering the EU under Regulation (EU) 2024/1787, and for LNG offtake agreements that specify an intensity threshold. Where that applies, an emissions reduction project has a revenue justification rather than only a compliance one.
Scope 1 versus Scope 2
Electrification moves emissions from direct on-site combustion, Scope 1, to purchased electricity, Scope 2. Under the GHG Protocol both are reported, and the net effect depends on grid carbon intensity. State which scope a project reduces, because moving emissions between categories is not the same as eliminating them.
Hazardous Area Classification and Interconnection
Generation equipment installed at an oil and gas facility sits inside or adjacent to a classified hazardous area, and the classification determines what equipment may be installed and where.
A hazardous area is a location where a flammable atmosphere may be present. In the United States, classification follows NFPA 70, the National Electrical Code, using the Class and Division system under Article 500 or the Zone system under Article 505. API RP 500 and API RP 505 provide the recommended practice for classifying locations at petroleum facilities under each system respectively. Internationally, the IEC 60079 series governs, with IECEx certification for equipment.
What this constrains
Generation packages are frequently sited outside the classified boundary for exactly this reason, which affects cable runs, voltage drop and land take. Where equipment must sit inside a classified area, it requires certification matching the zone or division, the gas group and the temperature class, and that certification must be verified on the nameplate at delivery rather than assumed from the order.
For turbines in process service, API 616, Gas Turbines for the Petroleum, Chemical and Gas Industry Services, governs the machine specification.
Interconnection
Where generation runs in parallel with the utility or exports power, IEEE Std 1547-2018, Standard for Interconnection and Interoperability of Distributed Energy Resources with Associated Electric Power Systems Interfaces, applies, with IEEE Std 1547.1-2020 defining conformance test procedures. Confirm the utility's adopted version and its Reference Point of Applicability before finalising the design.
A non-export configuration avoids much of that scope, and choosing it deliberately at feasibility rather than discovering it during the study saves months.
Permitting and insurance
Adding generation typically triggers an air permit review, and where it increases emissions it may trigger New Source Review. Insurers price on equipment type, protection systems, area classification compliance and maintenance regime. Engage both before equipment selection rather than after.
The Current Market and What It Changes
Market conditions changed materially during 2025 and 2026, and the change affects power decisions more than portfolio decisions.
Verified position as of the EIA September 2026 Short-Term Energy Outlook and the IEA Gas Market Report Q1-2026:
- Brent crude forecast to average around $90 per barrel in the second half of 2026, falling to an average of $74 per barrel in 2027, with Middle East production held below pre-conflict averages by Strait of Hormuz constraints
- Henry Hub forecast close to $3.70 per MMBtu in 2026, having averaged $3.6 in 2025, a 50 percent rise on 2024, and having spiked to $7.72 in January 2026 during Winter Storm Fern
- Global oil consumption forecast to decrease by an average of 1.2 million barrels per day in 2026
- US electricity sales reaching a record 4,135 billion kilowatt-hours in 2026
- An attack on the Ras Laffan LNG facility on 18 March 2026 damaged two liquefaction trains representing 17 percent of Qatari export capacity, with repairs estimated at up to five years.
What it means operationally
Higher and more volatile gas prices raise the opportunity cost of fuel gas burned on site, which strengthens the case for electrification and for associated gas capture. Record electricity demand tightens the interconnection and equipment queues you depend on. LNG supply disruption raises the value of every cargo, which raises the value of avoiding an unplanned outage.
A standing caution: these figures are dated and will move. Any capital decision should be tested against the current EIA and IEA releases rather than against a number in an article. That is why this section carries its sources and its date.
On the long-range question
Demand scenarios to 2050 are contested and depend heavily on policy assumptions. McKinsey's Global Energy Perspective has held that oil and natural gas continue to make up a significant share of the energy mix through 2050, partly because of how they combine cost-effectiveness and security of supply. Near-term data shows consumption declining modestly. Both can be true, and neither changes what an operator must do about power at a specific site this year.
How to Decide: The Site Power Assessment
Assess site power in the order that respects lead time: load first, supply options second, technology third, because the third decision is worthless if the second is unavailable.
Step one, define the load. Peak kW or MW, minimum load, load profile over a typical week, motor starting requirements, and whether the load is permanent, campaign-based or growing. Interval data beats nameplate every time.
Step two, test grid availability. Pull the utility hosting capacity map, then request a preliminary interconnection assessment. Establish the study timeline and any network upgrade contribution before assuming the grid is the answer.
Step three, establish fuel availability. Volume, composition, pressure and reliability of associated or pipeline gas, and whether it declines with production.
Step four, test the regulatory position. Which methane subpart applies, whether any deferred provision returns within the project life, and whether area classification constrains siting.
Step five, compare options on a consistent basis. Capital, operating cost including fuel or power at a realistic forward price, emissions by scope, schedule to energisation, and residual value or relocatability.
Step six, decide ownership and operations. Who owns the asset, who operates it, and how availability is measured and guaranteed.
What to require from a power partner
Evidence of comparable delivered projects in oil and gas service, not general power references. Hazardous area experience with certification handled rather than assumed. A stated schedule to energisation with the assumptions visible. Clarity on whether they will also operate the asset and on what terms.
For operations scope and delegation once the asset is running, see our guide to plant operations and maintenance, and for structuring the O&M arrangement, our guide to choosing an O&M provider.
Staffing and energy management
A site with generation needs an operating and maintenance regime it did not previously have. Where a formal framework is required, ISO 50001, Energy management systems, provides the management system standard, and it is increasingly referenced in corporate emissions commitments.
For sourcing the equipment and the sector compliance that attaches to it, see our guides to the industrial procurement process.
How the Decision Changes by Segment
The four forces apply across the value chain. Which one dominates changes with the asset.
Upstream
Pneumatic conversion and pad electrification dominate, and the defining constraint is that pads are numerous, remote and individually small. Solutions that work at one pad must scale to hundreds. Associated gas is frequently the obvious fuel and the obvious problem simultaneously.
Midstream
Compressor station electrification is the single largest opportunity and the largest load. Stations are fixed, well-characterised and often near existing network, which makes grid supply more viable here than upstream. Long linear assets make the interconnection question site-specific rather than system-wide.
LNG
Power demand is very large, continuous and critical, and electric drive for liquefaction trains is an established alternative to gas turbine drive. Emissions intensity directly affects market access under the EU framework, so the power decision and the commercial decision are the same decision.
Refining and petrochemicals
Existing power infrastructure is substantial, so the question is usually incremental rather than greenfield: cogeneration optimisation, waste heat recovery and reliability upgrades.
Offshore
Weight, footprint and certification constrain everything, and power from shore is an established alternative where a cable route exists. The cost of getting anything wrong is far higher, which raises the value of specification discipline.
Remote and stranded assets
No grid, no gathering, and frequently no road. Self-generation on associated gas is often the only option, and logistics rather than technology determines what is feasible.
Outside the United States
The physics and the equipment are unchanged. The regulatory driver differs: Regulation (EU) 2024/1787 governs methane monitoring, reporting and verification and import requirements in the EU, other jurisdictions have their own frameworks, and OGMP 2.0 operates as a voluntary international reporting standard. Confirm the local grid code and interconnection regime, which vary more than the equipment standards do.
What Prismecs Does
Prismecs delivers power infrastructure for industrial operators, including distributed and on-site generation, and serves oil and gas as a named vertical.
Relevant capability spans distributed energy solutions for microgrids and on-site generation, EPCM services for project delivery, power generation asset services for the equipment itself, and O&M services for running it afterwards.
Prismecs is OEM-agnostic and is not an equipment manufacturer, which means the recommendation between grid, self-generation and hybrid, and between engines, turbines and storage, is not tied to a product line.
Apply this article's criteria to any partner, including us. Ask for delivered projects in oil and gas service rather than general power references. Ask how hazardous area certification is handled and verified. Ask for a schedule to energisation with the assumptions stated. Ask whether they will operate the asset and on what availability terms.
To request a site power and electrification assessment, send your load profile or interval data, site location, available fuel, applicable methane subpart and required in-service date to sales@prismecs.com or call +1 (888) 774-7632. We return a supply options comparison, an indicative schedule and a regulatory constraint list.
Frequently Asked Questions
What does the energy transition actually mean for an oil and gas operator?
At site level it means four things: reduce methane emissions, reduce fuel consumption, reduce emissions intensity per barrel, and do all three without losing production. Three of the four are achieved by replacing something that burns gas with something that uses electricity, which makes it a power infrastructure problem. Corporate portfolio strategy is a separate decision made by different people.
Why does methane regulation create a power requirement?
Because the replacement for a gas-driven pneumatic controller needs power. 40 CFR Part 60 Subpart OOOOb emphasises adoption of advanced technologies for pneumatic controllers and pumps, pushing operators toward zero-emission systems. Electric actuation needs site electricity and instrument air needs a compressor, which also needs electricity. A wellpad running gas-driven pneumatics typically has no electrical service at all.
What is a zero-emission pneumatic system?
It is a control system that does not vent natural gas to actuate valves. The three routes are electric actuation, instrument air in which a compressor supplies clean dry air instead of produced gas, and nitrogen supplied from bottles or a cryogenic vessel. The first two require electrical power at the site. The third requires a continuing delivery schedule to a remote location.
What is Subpart OOOOb and what does it cover?
40 CFR Part 60 Subpart OOOOb is the EPA New Source Performance Standard for crude oil and natural gas facilities whose construction, modification or reconstruction commenced after 6 December 2022, published at 89 FR 17043 on 8 March 2024. It establishes standards for methane as a greenhouse gas and for volatile organic compounds and sulfur dioxide. Subpart OOOOc provides emissions guidelines for existing sources, implemented through state plans.
What is a super-emitter event and when do the provisions apply?
A super-emitter event is any emissions event at or near an oil and natural gas facility, detected using remote detection methods, with a quantified emission rate of 100 kilograms per hour of methane or greater. On EPA notification, the operator must act within five calendar days. The provisions do not apply between 31 July 2025 and 22 January 2027, and apply after 22 January 2027.
Is the US methane regulatory position stable?
No. The Waste Emissions Charge was repealed by Congressional Review Act action and Congress prohibited EPA from collecting it until 2034. EPA proposed delaying the Greenhouse Gas Reporting Program Subpart W until 2034 and in November 2025 finalised deadline exemptions for certain OOOOb and OOOOc provisions. Confirm current obligations with your air permitting adviser rather than relying on any published summary.
Should I take power from the grid or generate on site?
Schedule usually decides. Grid supply suits permanent load near adequate network where the interconnection timeline fits the project. Self-generation suits cases where the grid cannot serve the load in time, where fuel is available on site, or where the location is remote. Check the utility hosting capacity map and request a preliminary interconnection assessment before assuming grid supply is available.
Why has grid supply become harder to secure?
Competition for the same capacity. EIA forecasts US electricity sales reaching a record 4,135 billion kilowatt-hours in 2026, almost 2 percent above 2025, driven by data centre development and increased manufacturing. Oil and gas operators now queue for the same interconnections, transformers and switchgear as data centre developers who move faster and pay more. That competition, not technical limits, drives most self-generation decisions.
Does electrification actually reduce emissions?
It reduces Scope 1, direct on-site combustion, and increases Scope 2, purchased electricity. Under the GHG Protocol both are reported, and the net effect depends on the carbon intensity of the supplying grid. Where the project also removes venting, as with pneumatic conversion, the methane reduction is real and direct. Be explicit about which scope a project reduces.
Can associated gas power my own operations?
Often yes, and it addresses flaring at the same time. Three constraints apply. Composition is wet and variable and usually requires a conditioning skid before it meets generator fuel specification. Volume declines with the production curve, so modular relocatable capacity beats one large unit. Production upsets interrupt fuel supply, so dual fuel or a grid backup protects against an outage caused by the process being served.
What is e-frac and how is it powered?
Electric fracturing replaces diesel-engine-driven pressure pumping with electric motors, typically drawing tens of megawatts for the duration of a completion. The load is large, short and mobile, which suits temporary or relocatable generation rather than a permanent grid connection. It is the clearest case in the sector where the power solution moves with the operation rather than the reverse.
What hazardous area standards apply to generation at an oil and gas site?
In the United States, NFPA 70 provides the Class and Division system under Article 500 and the Zone system under Article 505, with API RP 500 and API RP 505 giving recommended practice for classifying petroleum facility locations under each. Internationally the IEC 60079 series applies with IECEx certification. Generation packages are frequently sited outside the classified boundary for this reason.
Does adding generation trigger permitting?
Usually. Adding combustion capacity typically triggers an air permit review, and where it increases emissions it may trigger New Source Review. Where the generation runs in parallel with the utility or exports power, IEEE Std 1547-2018 governs interconnection, with IEEE Std 1547.1-2020 defining conformance tests. A non-export configuration avoids much of that scope and should be chosen deliberately at feasibility.
Can renewable energy completely replace oil and gas?
Not in the near term. Oil and gas remain critical for petrochemicals, aviation and heavy industry where alternatives are limited or immature. McKinsey's Global Energy Perspective has held that oil and natural gas continue to make up a significant share of the energy mix through 2050, partly because of how they combine cost-effectiveness and security of supply, while near-term data shows consumption declining modestly. Both positions can hold simultaneously.
Tags: Oilfield Electrification Subpart OOOOb Compliance Associated Gas to Power Field Power Infrastructure Methane Intensity
recent posts
Power Utilities
18 minutes read
Temporary and Bridge Power for Industrial Facilities: When and How to Use It
Planning bridge power past 12 months? Under EPA rules your generators may be stationary from day one. Check Tier 4, NSPS KKKKa and SPCC triggers befor...
Power Utilities
16 minutes read
What Is a Mobile Gas Turbine Power Plant? TM2500-Class Units Explained
A mobile gas turbine power plant is a transportable power generation system designed to add electrical capacity faster than a conventional permanent p...
Power Utilities
20 minutes read
Fast-Track Power Plants Deployment: How to Reach Speed to Power in Under 12 Months
Fast-track power plant deployment can hit first power in weeks. See real TM2500 timelines from permitting to COD, proven in Oman and Taiwan. Plan your...
O&M Services
11 minutes read
Gas Turbine Outage Planning: Schedule, Scope Rules, and Checklist
Gas turbine outage planning starts 18 months out. Get the T-minus schedule, scope freeze rules, parts readiness gates and checklist. Talk to a Prismec...